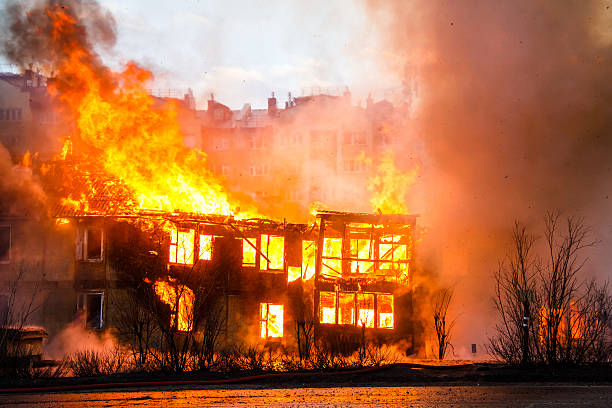
Imagine you are standing in front of a burning building, seeing your life work go up in flames. It all started years ago for you. In this classroom at Erasmus University, you and your teammates started working diligently to turn ideas and drafts into reality. On demo day, you managed to convince the whole audience your idea was the most promising. In 2027 you managed to win the Philips Innovation award and with this 50.000 euro of startup budget, you managed to scale your AI tool towards new heights. Years later, the company was founded and disrupted the industry, leading to massive growth and revenues. You just purchased a new building, taking much time to build a future proof home. However, last night one of the employees forgot to turn off their temporal space heater, which caused a short circuit.
Fortunately, you had insurance, or at least, you thought you did.
These days many insurance companies are faced with problems in complex risk environments. These problems come from changing technologies, such as artificial intelligence. According to a report by Swiss Re Institute (2026), natural accidents including fires and water breaks account for almost $107 billion in insured losses worldwide in 2025. To put this in perspective, total economic damage almost reached $220 billion, meaning that more than half of the damage was uninsured.
The process of insuring companies can be difficult. Especially since brokers need to estimate risk, handle large amounts of documents and assess the company’s assets. Especially for SMEs this can be challenging. But what if an AI agent could do all this work for you? That was the starting point of our idea. When we began our project, we first wanted to identify the problem. Luckily, one of our teammates worked at the company we wanted to design the tool for, which gave us access to inside information (such as company data, and company style templates) we otherwise would not be able to get. He could talk us through the bottlenecks in the organization, the resources and its focus.
Through discussion and with the help of insights provided by Howden, we were able to determine one interesting problem: it is relatively costly to serve smaller businesses. Brokers spend a lot of time on documentation, risk evaluation and insurance selection. In the case of smaller firms, the income that comes from these operations may not cover the effort invested. Our idea was a tool that automatically scans and identifies these documents and gives a risk assessment complemented with an overview of possible insurers. It is worth mentioning that McKinsey & Company (2024) has pointed out the great potential of generative AI in insurance due to the high volume of unstructured documentation. We aimed at making the life of insurance professionals easier, not replacing them. The hard thing here was to find an application of AI that is both innovative and commercially feasible.
Looking back, our project turned out to be more complex than we had initially thought. We first wanted to lay our focus on creating a tool that could be used by managers to monitor the performance of their brokers. However, in the discussion we realized that it would be more valuable to target the brokers themselves. As a result, we concentrated on document analysis and risk assessment. For me this was an important realization – when developing an AI strategy, it’s not always necessary to find the most innovative technology, it’s more about seeing how the technology solves a business problem or adds value to the company. Another important decision for us was to change our focus on deliverables. First, we invested a lot of time in building a strong presentation. Later, we realized that building a working prototype would be more effective, especially for demo day, where students value a working example over in-depth slides. Therefore, we chose to create a prototype of our tool. It had many versions, as our understanding of the task grew. However, I think that this extra effort paid off.
Reflecting on our project, I found the development of the project different from our expectations at the beginning. A lot of changes came during the development of our tool. This had an impact on our teamwork. To start, there was a lot of discussion about task distribution. In general we spent more time on distributing tasks in the beginning than working on the actual tasks themselves. This gave us a bit of a delayed start but after the route map was set, we kicked off fast. Here, it became clear to me how essential planning is, but also how excessive planning can have a negative impact and might slow things down.
My task in this project was to create the business case and economic perspective. So basically the way we would earn back this AI tool and the financial reasoning behind it. I created an Excel workbook, which contained comparisons between the traditional manual brokerage process and our new AI-powered approach. In order not to make any unrealistic assumptions, I considered three scenarios: conservative, base, and favourable. This model estimated costs per each insurance line, break-even premiums, possible improvement of capacity, cash impact, and break-even point in terms of the number of users.
In terms of teamwork, we all learned that communication is key. Because of our fast start, we all started developing slides independently. This caused some discrepancies in slides, which meant that a lot of work had to be redone. Also, multiple versions of slides, excel workbooks data, and prototypes were circulating within the group, leading to different team members using different materials, which only made things worse. Fortunately, a long meeting with clear agreements got everyone aligned again. Besides that, we had to be honest about our tool not making money in the first year and the fact that feasibility would only arise in the case of heavy usage. However, in the end these realizations helped us to focus on what would actually make the project work.
Perhaps the most important lesson I learned from this project relates to the connection between AI and human responsibility. On the one hand, our prototype showed how AI can make people’s work faster and less boring. On the other hand, decisions in the field of insurance have serious implications for people. So the European Insurance and Occupational Pensions Authority (EIOPA, 2025) draws attention to governance, accountability, and human involvement in AI mainly within insurance.
Coming back to the burning building. Imagine an algorithm had checked its insurance policy and determined that everything was good. But after the building burned down, people find out that an essential exclusion was missed in their policy. Whose fault is that? The algorithm’s? The broker’s? The company’s?
The point was that for me it was obvious that technology should serve people and assist in making professional decisions. However, it should never take the responsibility from them. Humans should always stay in charge, the so-called Human-in-the-Loop (HITL). Only then we can ensure that decisions remain accountable and that the underlying risks are mitigated. Trusting blindly on algorithmic systems supporting decisions leaves no margin for error. Just like bursting flames don’t like waiting.
European Insurance and Occupational Pensions Authority. (2025, August 6). Opinion on artificial intelligence governance and risk management. https://www.eiopa.europa.eu/publications/opinion-artificial-intelligence-governance-and-risk-management_en
McKinsey & Company. (2024, November 20). The potential of gen AI in insurance: Six traits of frontrunners. https://www.mckinsey.com/industries/financial-services/our-insights/insurance-blog/the-potential-of-gen-ai-in-insurance-six-traits-of-frontrunners
Swiss Re Institute. (2026). Natural catastrophes in 2025: The persistent rise of wildfire and storm risk (Sigma No. 1/2026). https://www.swissre.com/institute/research/sigma-research/sigma-2026-01-natcat-2025-wildfire-storm-risk.html
